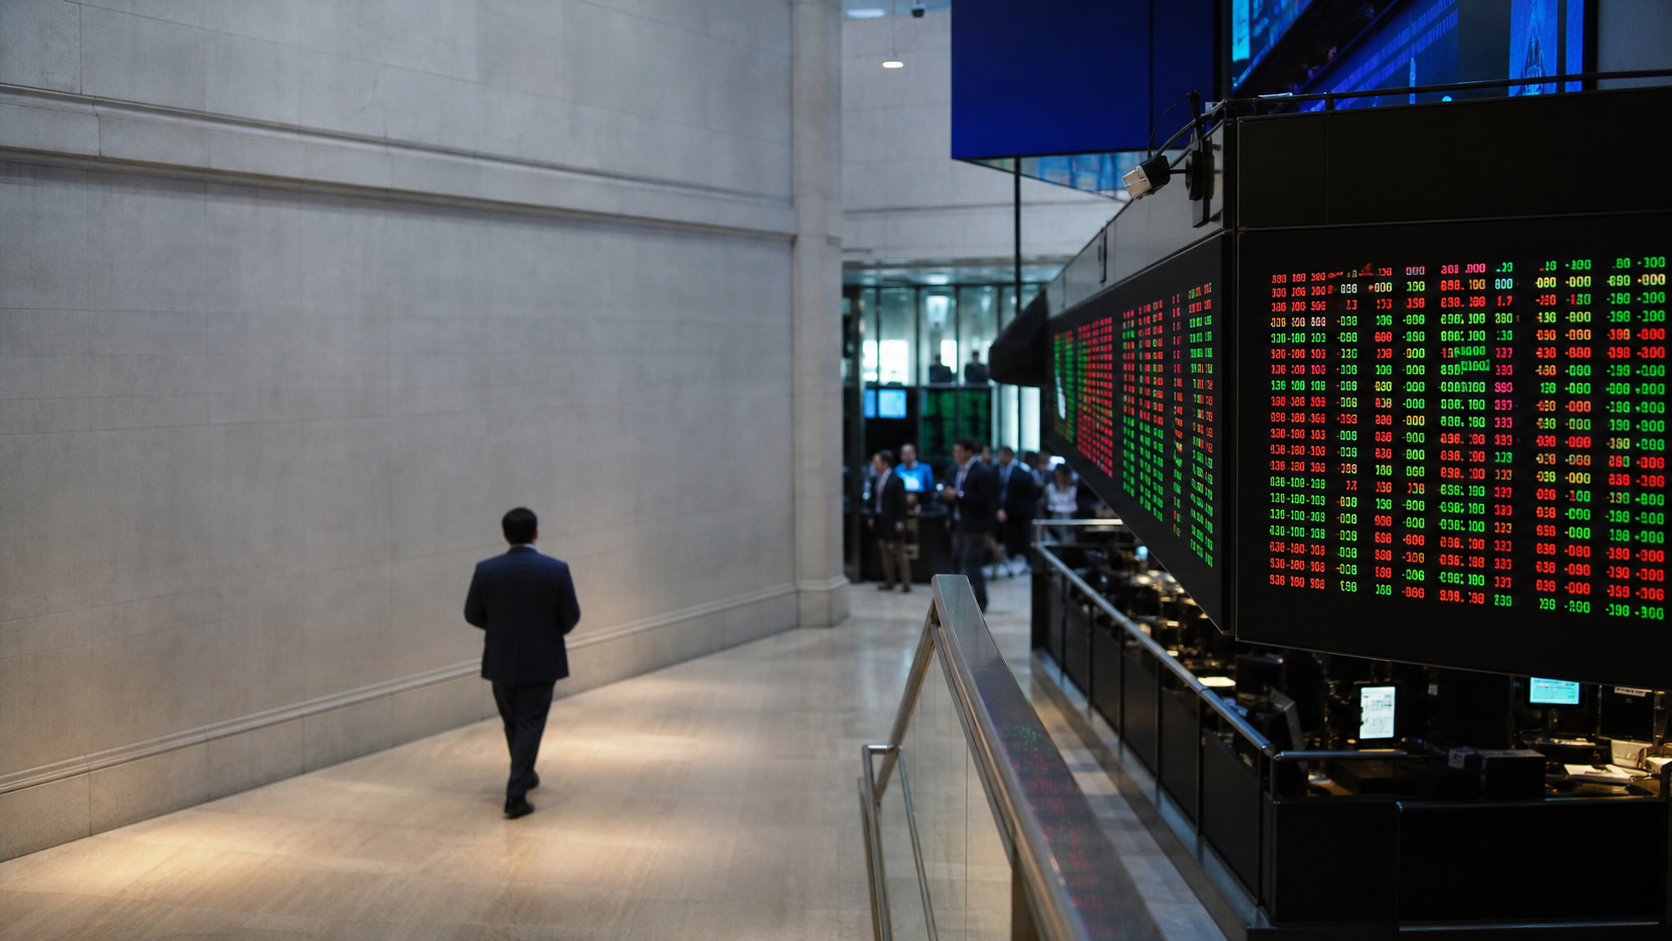
Indian equities recorded a broad sell-off at the close on Thursday, 24 September 2026. The Nifty 50 ended at 23,063.10, down 383.70 points, or 1.64%, while the BSE Sensex closed at 73,580.54, lower by 1,247.71 points, or 1.67%. The Hindu BusinessLine’s session report identified renewed crude strength, higher U.S. bond yields and persistent geopolitical uncertainty as the principal pressures on investor sentiment. [1]
The market status was therefore a verified one-day decline, not evidence of a formally declared change in policy or a confirmed new economic regime. Brent crude had returned to about $106 a barrel after being near $98 the previous day, while the U.S. 10-year Treasury yield moved to around 5.11%. Those moves raised concerns about inflation, borrowing costs and the pace of global monetary easing as Indian stocks came under pressure. [1]
Key points
- The Nifty 50 closed at 23,063.10, down 1.64%, on 24 September. [1]
- The Sensex finished at 73,580.54, down 1.67%, a decline of 1,247.71 points. [1]
- Brent crude rebounded to around $106 a barrel from roughly $98 on Wednesday. [1]
- The U.S. 10-year Treasury yield rose to about 5.11%, intensifying concern over global funding costs. [1]
- Almost all NSE sectoral indices ended lower; private banks, metals and autos were among the sharper areas of weakness. [1]
What happened at the close
The closing figures show that selling was both substantial and broad. The Nifty’s 383.70-point fall and the Sensex’s 1,247.71-point decline were accompanied by weakness across most sectoral gauges, rather than being confined to one isolated pocket of the market. BusinessLine described the session as sharp selling pressure on Indian equities, with the combination of commodity, rates and geopolitical concerns weighing on sentiment. [1]
That distinction matters when reading the day’s outcome. The report establishes the closing levels and the market’s stated drivers; it does not establish that one factor alone caused every stock to decline. Nor does a single close, however large, by itself establish a lasting direction for the broader market. The verified development is the extent of the 24 September retreat and the external pressures present during that session.
Crude moved back toward the session’s focus
Brent crude was reported near $106 a barrel after falling to around $98 on Wednesday. [1] The rebound put energy prices back at the centre of the market narrative. For equity investors, a higher crude price is relevant because it can renew concern about inflation and the cost of running businesses, especially when the move occurs alongside a rise in global bond yields.
The article’s wording is important: it linked the sell-off to renewed crude strength rather than presenting the commodity move as a complete explanation. The report also displayed Indian crude futures at 8,997, up 172 points, providing a domestic-market indication of the same energy pressure. [1] That figure is a quoted market display for the session, not a forecast of where oil will trade next.
U.S. yields raised the cost-of-capital concern
The U.S. 10-year Treasury yield rose to around 5.11%, according to the market report. [1] BusinessLine said the move increased concern about inflation, borrowing costs and the pace of global monetary easing. The yield is a benchmark watched well beyond the United States: when longer-term government borrowing costs rise, investors reassess the relative appeal and valuation of risk assets around the world.
The report also noted that the U.S. 30-year Treasury yield reached 5.4% and that the five-year yield briefly crossed 5% before settling at its highest level since 2007, citing market commentary. [1] These readings provided a broader rates backdrop for the 10-year move, but they should not be confused with Indian borrowing rates or with a policy decision by the Reserve Bank of India. The reported market reaction was an international rates shock transmitting into Indian equities.
How the pressure spread across sectors
The sector pattern showed a broad risk-off response, with the sharpest declines reported in auto, metal and private-bank stocks. The Nifty Auto index fell 1.46%, Nifty FMCG declined 1.18%, Nifty IT lost 0.67%, Nifty Media fell 0.75%, Nifty Metal dropped 1.99%, Nifty Pharma slipped 0.46% and Nifty PSU Bank declined 1.21%; the Nifty Private Bank index lost more than 2%. [1]
This spread helps explain why the headline indices fell together. Metals and autos were among the areas directly identified as weak in the report, while private banks recorded a decline of more than 2%. The cross-sector pattern indicates that the session was not simply a commodity-stock rotation. Instead, investors were repricing exposure across cyclical, financial and defensive groups as the external rates and energy backdrop deteriorated. The figures describe market performance; they do not prove that every company in a sector was affected for the same reason.
Why the combination mattered
Crude and Treasury yields can transmit through different channels at the same time. Higher energy prices intensify the market’s inflation discussion, while higher long-term U.S. yields make global funding conditions less accommodative and can alter how investors value future earnings. BusinessLine explicitly connected the session to concerns about inflation, borrowing costs and global monetary easing. [1]
The significance of 24 September was therefore the interaction of pressures rather than the direction of one indicator in isolation. Oil had reversed part of its previous-day decline, the U.S. 10-year yield was near 5.11%, and geopolitical uncertainty remained part of the reported backdrop. [1] Together, those conditions gave investors fewer reasons to ignore macroeconomic risk, which was reflected in the nearly universal decline among NSE sectoral indices.
What remains uncertain
Several conclusions cannot be drawn from the verified session report. It does not show whether the crude move will persist, whether the rise in U.S. yields represents a sustained repricing or a short-term market move, or whether Indian equities will repeat the same decline in later sessions. It also does not isolate the contribution of geopolitical developments from the effects of oil and rates.
The report included analyst commentary and index levels, but commentary about support, resistance or future market behaviour is not treated here as an outcome. The available evidence supports a description of what happened on 24 September and why the cited factors mattered at that time. It does not support trade recommendations, price targets or a forecast.
What to monitor next
The next meaningful status checks are observable market data rather than a predicted outcome: the subsequent Brent settlement, the direction of the U.S. 10-year Treasury yield, and whether the Indian sector pattern remains broad or becomes concentrated. The relationship between those indicators and later index closes will show whether the 24 September shock was absorbed or extended, but that determination requires subsequent sessions.
For this report, the confirmed position remains unchanged: Nifty and Sensex finished sharply lower on 24 September 2026, crude was back near $106 a barrel, the U.S. 10-year yield was around 5.11%, and almost all sectoral indices declined. [1] The market’s uncertainty lies in duration and transmission, not in the closing figures themselves.